Skip to content
Amy JenkinsSep 25, 2026, 8:08:25 AM5 min read

Arrears Charging in Motor Finance: what our market benchmark revealed

INTRODUCTION

THE CASE study

When considering whether arrears and late payment fees deliver fair value for customers, understanding current market practice is only part of the picture.

A UK Motor Finance lender commissioned Map Room to conduct an independent benchmarking review of arrears charging practices across the sector. The review examined charging structures, operational approaches and conduct considerations, assessing the findings through the lens of Consumer Duty, Fair Value and customer outcomes.

The benchmark revealed that only two firms in the sample applied arrears or late payment fees, highlighting a notable shift in market practice and raising important questions for firms reviewing their own charging strategies

ARREARS-CHARGING IMAGE
AT A GLANCE

CUSTOMER

A UK Motor Finance lender reviewing its approach to arrears and late payment fees.

WHAT WE DID

Conducted an independent market benchmark across UK lenders.

KEY FINDING

Only 2 firms in the sample applied arrears or late payment fees

[learn more below]

THE CHALLENGE

INDEPENDENT view...

Our customer is a UK Motor Finance lender seeking an independent view of current market practice for arrears and late payment fees.

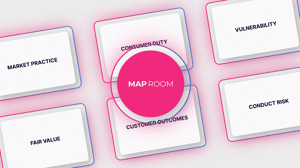
The objective was not simply to understand what other lenders charged. The firm wanted to determine whether its own approach remained appropriate when considered against market practice, Consumer Duty requirements, Fair Value expectations, customer outcomes, vulnerability considerations and broader conduct risk. 


The review therefore needed to provide more than a market comparison. It needed to create an evidence-based view of how arrears charging is evolving across Motor Finance - and what that means for firms seeking to demonstrate good customer outcomes.


Arrears Charging Framework Cover Image
OUR APPROACH

WHAT WE did

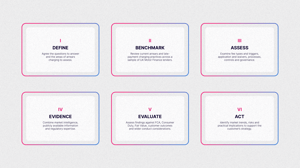
Map Room conducted an independent benchmark of arrears charging practices across a sample of UK Motor Finance lenders, examining the end-to-end customer journey rather than looking at fees in isolation.

The review considered:

  • fee types and charging triggers;

  • fee application and waiver practices;

  • collections and operational processes;

  • Fair Value assessments;

  • governance arrangements; and

  • regulatory and conduct considerations.

We combined market intelligence and publicly available information with regulatory expertise, assessing the findings against relevant FCA expectations and our broader experience of customer outcomes and conduct risk.

This gave the customer an objective view of both what the market was doing and what those practices meant from a regulatory and customer-outcome perspective.

OUR BENCHMARK PROCESS IMAGE
KEY FINDINGS

WHAT WE discovered

The benchmark showed a clear market trend away from arrears charging - but also demonstrated that there is no single approach across the sector. 

KEY FINDING

Only Two Firms Applied Arrears or Late Payment Fees.
The benchmark identified only two firms that applied arrears or late payment charges, suggesting a significant move away from traditional arrears charging models across the sector.

KEY FINDING

No Firms Charged for Failed DDs or Arrears Correspondence.
None of the firms reviewed charged customers for failed Direct Debits or arrears-related communications.

KEY FINDING

Interest Treatment Was Generally Consistent.
Where arrears fees were charged, the fee itself was not subject to interest. However, firms generally continued to charge contractual interest on missed payments.

KEY FINDING

Customers Were Given Repayment Flexibility.
All firms provided customers with options to repay missed payments or manage arrears over time.

KEY FINDING

Recovery Costs Remain More Common.
Six firms passed some form of recovery or repossession-related costs to customers, while two firms stated they did not.

KEY FINDING

Approaches to Financial Difficulty Support Varied.
There was significant variation in the extent of support available to customers experiencing financial difficulty, including differences in the information publicly available to customers.
Map Room Primary Logotype Transparent Sized-1

THE ARREARS CHARGINGgood practice guide

Good practice starts with more than the fee.

Our Arrears Charging Good Practice Guide brings together the key considerations firms should work through when reviewing arrears and late payment charging - from Fair Value and vulnerability to customer outcomes and operational controls

Good Practice Guide Mockup 1 white bg
What Does This Mean for Motor Finance Firms?

The review identified a clear market trend away from arrears charging. However, it also demonstrated that there is no single approach adopted across the sector.

Where firms charge arrears fees, or are considering introducing, changing or removing them, the decision should not be viewed solely as a pricing exercise.

Instead, firms should consider:

  • Fair Value outcomes;
  • proportionality of charges;
  • customer vulnerability;
  • customers in financial difficulty;
  • customer-level impacts;
  • operational controls and governance; and
  • their ability to evidence good customer outcomes.

This is particularly important where firms may be required to demonstrate how charging practices align with Consumer Duty expectations.

CONCLUSIONS

THE outcome

The review provided the customer with an independent evidence base to support decision-making around its arrears charging strategy.

Map Room Delivered: 

OUTCOME

A clear view of current market practice for arrears charging.

OUTCOME

Insight into evolving regulatory guidance & expectations.

OUTCOME

Analysis of conduct and Consumer Duty considerations.

OUTCOME

Controls & governance guidance for arrears charging frameworks.

The firm was able to assess its position against the wider Motor Finance market and better understand the evidence required to demonstrate fair customer outcomes.
QUOTE IMAGE BG
AN IMPORTANT PIECE OF analysis...

"It was great to lead this work and I'd like to thank our customer for trusting us with such an important piece of analysis. I'd also like to thank every firm that contributed to the benchmark. We were able to speak with organisations from across Map Room's wider customer network, as well as firms we hadn't worked with before, which helped us build a much broader and more representative view of current market practice.

Those conversations gave us the depth of insight to move beyond simply comparing charges and really understand how different firms are approaching customer outcomes, Fair Value and arrears support."

AMY JENKINS | HEAD OF REGULATORY EXCELLENCE | MAP ROOM

CAN YOU EVIDENCE THAT your approach is working?

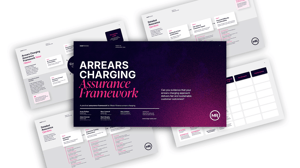
Our Arrears Assurance Framework helps firms assess the controls, governance and evidence underpinning their approach to arrears - including Fair Value, Consumer Duty, customer outcomes, financial difficulty and vulnerability, operational controls and outcome testing.

Assurance Framework Mockup 3 white

Our benchmarking work gives firms something they rarely get from looking at their own operation alone: wider market context. But the real value comes from understanding what that context means for your customers, your controls and your ability to evidence good outcomes...


We’ve included a wider suite of practical assets and resources on this page to help firms go further - and where more tailored support is needed, we’re happy to hold conversations about the specific challenge.

- AMY JENKINS | HEAD OF REGULTORY EXCELLENCE

OTHER case studies...